⚡ Done-for-you growth — we run GoHighLevel & your social so you don't have to · No contract
Book a Demo →

First-time homebuyer mortgage websiteDesign 3 of 18 · browse them all →

First-time buyers who already understand the loan

Plain-English guides to every route to a first set of keys, so your calls start at "when can we apply" instead of "what is PMI".

Pages
77
Screens below
6
Status
Live
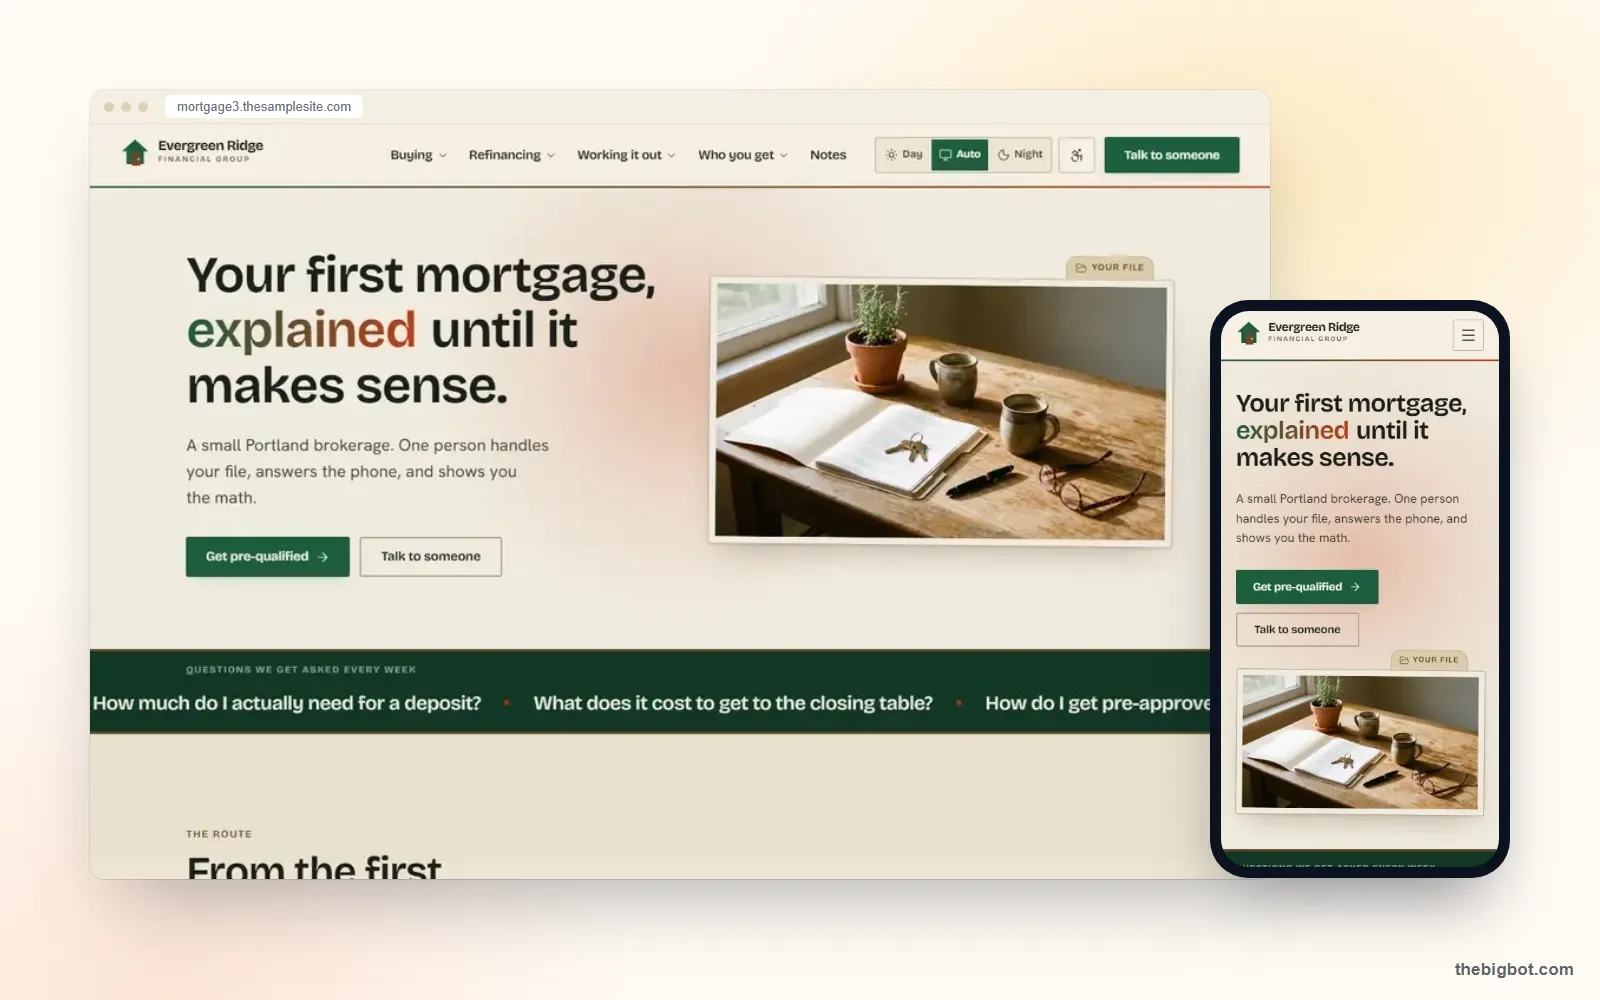
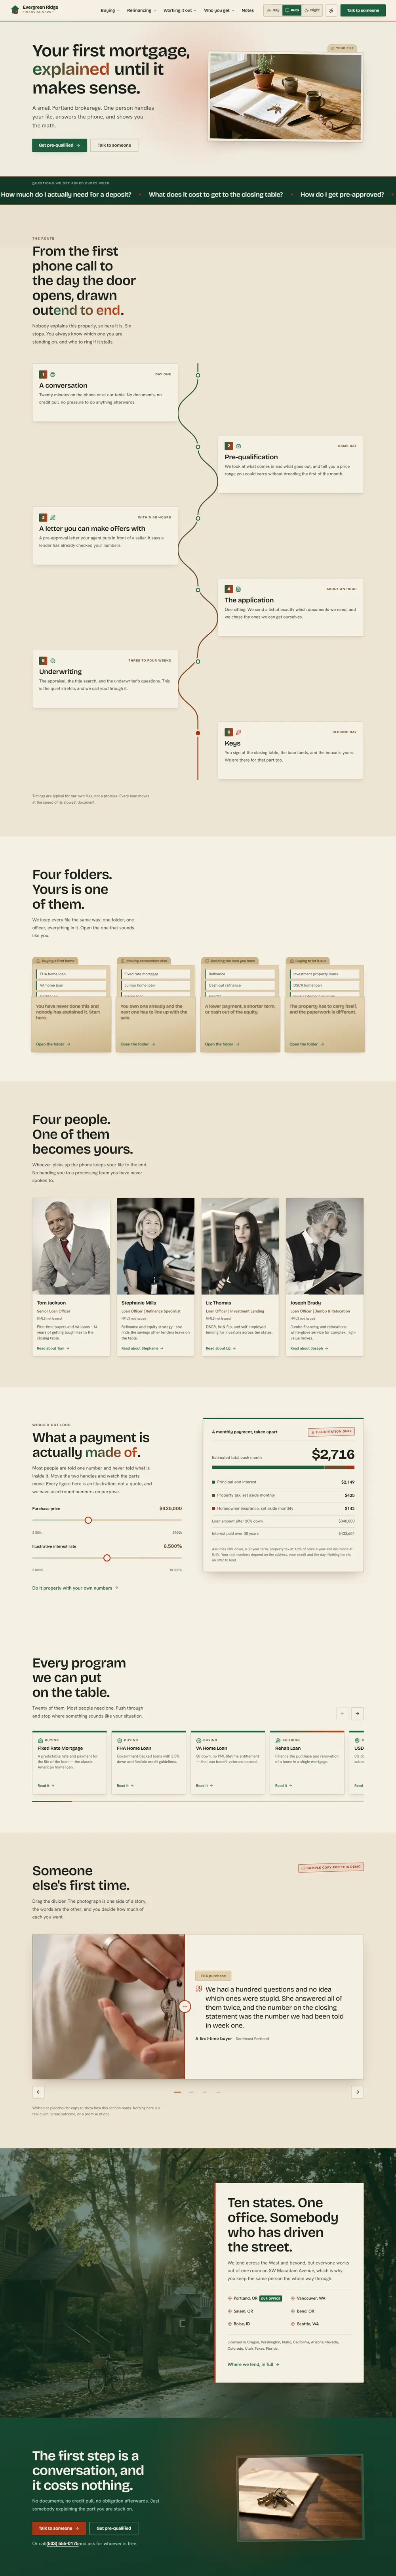
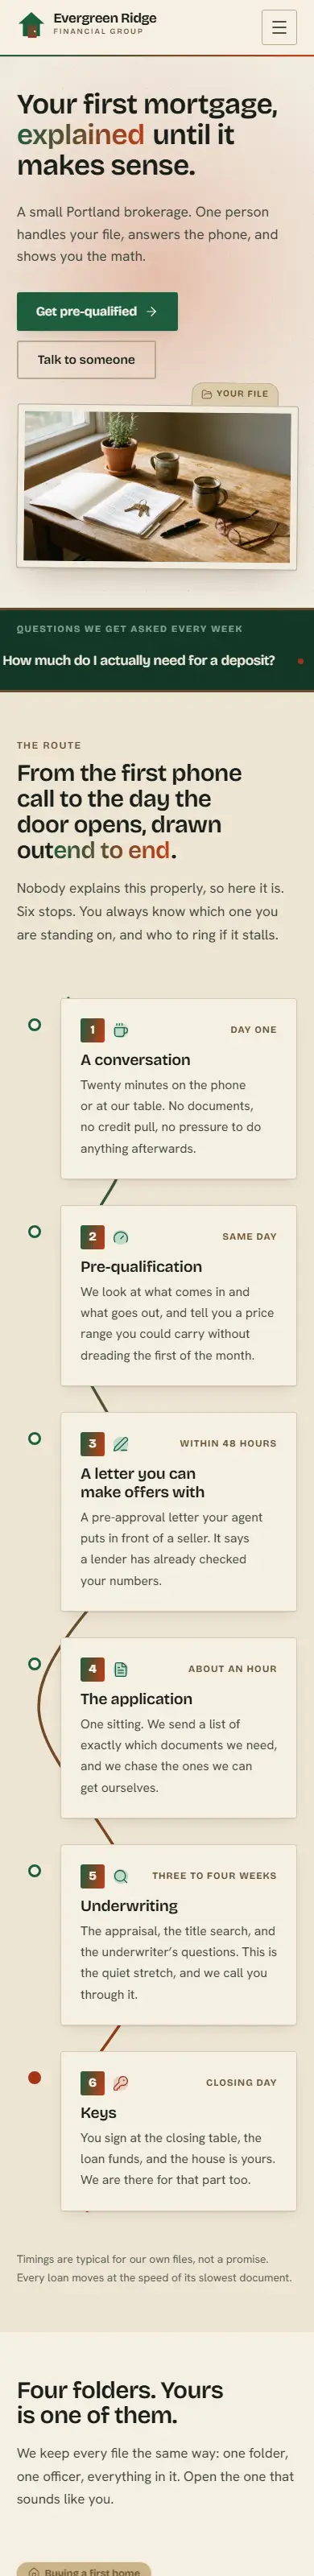
Evergreen Ridge mortgage website design shown on a desktop browser and a phone

Where Evergreen Ridge wins

Evergreen Ridge is written for a small brokerage whose borrowers are buying for the first time. The navigation starts with buying, refinancing and working it out, and every loan type is explained before it is sold.

Brokerages that specialize in first-time buyers

Plain words before products

Every loan type is explained in a sentence a first-time buyer can repeat to their partner, which is what gets forwarded and linked to.

A start-here path

The navigation opens with buying, refinancing and working it out, so a nervous visitor is never asked to choose a product they cannot name yet.

A named person on the file

Team pages promise one loan officer per file, which is the differentiator small brokerages actually win on.

Also on the site

Start-here guidance. A first-time buyer path that explains terms before asking for an application.

Program explainers. FHA, VA, USDA, low down payment and jumbo pages written in plain words.

One loan officer per file. Team pages that show borrowers exactly who will handle their loan.

Day and night reading modes. Light, dark and device-following themes for comfortable long reads.

The five programs a first-time buyer site has to explain

Most first-time buyers assume they need 20% down. These are the routes that say otherwise, and the questions your site should answer before the first call. Figures are program rules as of 2026; your rate sheet and overlays decide the rest.

FHA

3.5% minimum down

Mortgage insurance
1.75% upfront plus 0.55% a year for most loans
Who qualifies
Credit score of 580 or higher for 3.5% down. Open to repeat buyers too.
Conventional 97

3% minimum down

Mortgage insurance
Private mortgage insurance, removable once you reach 20% equity
Who qualifies
At least one borrower must be a first-time buyer. No income limit.

HomeReady / Home Possible

3% minimum down

Mortgage insurance
Reduced private mortgage insurance coverage
Who qualifies
Income at or below 80% of the area median. Homebuyer education required.

VA

0% minimum down

Mortgage insurance
No monthly mortgage insurance. One-time 2.15% funding fee on a first use with under 5% down
Who qualifies
Eligible veterans, service members and some surviving spouses. Fee waived with a service-connected disability rating.

USDA

0% minimum down

Mortgage insurance
1% upfront guarantee fee plus 0.35% a year
Who qualifies
Home in an eligible rural area and household income at or below 115% of the area median.

Sources: HUD Mortgagee Letter 2023-05 (FHA premiums), Fannie Mae 97% LTV options, VA funding fee, USDA guaranteed loan program.

What changes when it becomes yours

You are not buying a template to fill in. We rebuild this design around your business, then wire it to the system that answers and follows up.

Included in both plansThe website, the CRM behind it and the AI receptionist answering the phone come with Authority Launch and Authority Pro. No separate website fee.
  1. Your identity replaces the demo lender. Logo, colors, photography, NMLS number, licensed states and the disclosures your compliance lead signs off.
  2. Your programs, not ours. Pages you do not offer come out, pages you do offer get your terms, and the calculators are set to your assumptions.
  3. Every form reaches a person. Pre-qualification and contact forms land in the mortgage CRM, and the first text and email go out inside 60 seconds.
  4. The phone stops ringing out. The AI receptionist answers borrower and realtor calls day and night and books the consult on a licensed loan officer's calendar.
  5. It goes live on your domain. Launch in 3 days, Pro in 7, from the day we have your details. See pricing.

Pick Evergreen Ridge if

And if one of these is not you, the design next to it probably fits better. We would rather launch the right one.

  • Most of your pipeline is buying for the first time
  • You spend calls explaining what FHA, PMI and escrow actually mean
  • You want to be the lender who explained it, not the one who quoted fastest

Questions about Evergreen Ridge

Why is Evergreen Ridge good for first-time buyers?
+
It explains each loan type in plain language, starts visitors on a first-time buyer path and keeps calculators and guides one click away.
Can Evergreen Ridge include my team?
+
Yes. The team pages are rebuilt with your loan officers, photos and NMLS numbers.
Which loan programs should a first-time buyer mortgage website explain?
+
At minimum FHA, VA, USDA, Conventional 97 and HomeReady or Home Possible. Those five cover the low and no down payment routes most first-time buyers ask about, from 3.5% down on FHA to 0% down on VA and USDA.
Do first-time buyers need 20% down?
+
No. Conventional 97 and HomeReady allow 3% down, FHA allows 3.5% with a 580 credit score, and VA and USDA allow 0% down for eligible borrowers. Putting less than 20% down usually means paying mortgage insurance or a guarantee fee.
Is this mortgage website included with TheBigBot?
+
Yes. Your website is included with Authority Launch and Authority Pro. We rebrand the design you pick with your logo, colors and NMLS details and connect every form to your CRM.
How long does it take to launch?
+
Authority Launch goes live in 3 days and Authority Pro in 7 days, counted from the moment we receive your onboarding details.

Launch Evergreen Ridge as your website.

We rebrand it, connect it to your CRM and put it live in days.

Book a Demo →